Datadog earnings beat forecasts, but a flat sales outlook clouds growth
Earnings results
- EPS beat +26.6%
Actual: $0.81 · Cons.: $0.64 (Non-GAAP diluted EPS; FactSet consensus reported November 4)
- Revenue beat +4.1%
Actual: $1.19709B · Cons.: $1.15B (Reported revenue; rounded FactSet consensus reported November 4)
- Guidance
Raised 2026 revenue to $4.515–4.525 billion from $4.45–4.47 billion and adjusted EPS to $2.73–2.75 from $2.50–2.54. Issued Q4 revenue of $1.19–1.20 billion.
Earnings and the stock move
Datadog released third-quarter earnings before open on November 4. Revenue and adjusted profit exceeded dated analyst estimates, and full-year guidance rose. However, the newly issued fourth-quarter revenue range is nearly unchanged from third-quarter sales and implies slower year-over-year growth. Management’s contractual-minimum assumption for its largest customer and pricing effects from early renewals explain why usage and forecast caution remain central to the investment decision. Contemporary financial reporting linked the decline to the sales outlook rather than treating a strong historical quarter as sufficient reassurance.
Q3 2026 ended September 30 earnings recap
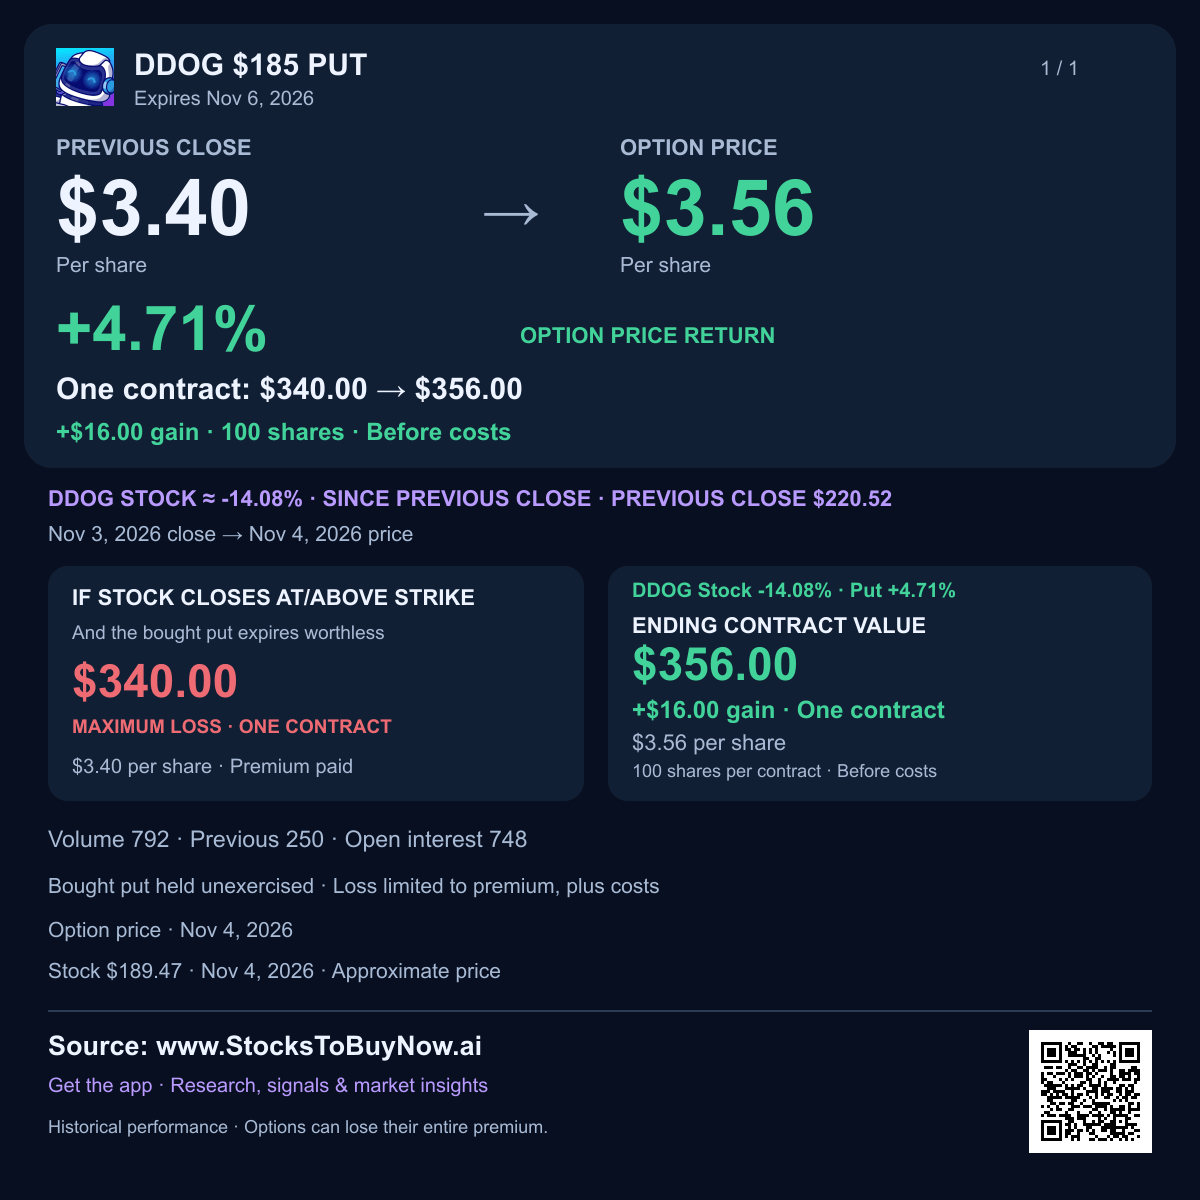
Datadog’s earnings beat forecasts, but its next-quarter sales outlook points to little growth from the latest quarter. The price used for this comparison fell about 13.4% versus the previous close during trading on November 4.
- Third-quarter revenue reached $1.2 billion, about 4.1% above the $1.15 billion analyst estimate. Sales grew 35% from a year earlier; that growth rate is separate from the forecast beat.
- Adjusted earnings per share, or profit per share, were $0.81 versus $0.64 expected, a 26.6% beat. Profit under standard accounting rules was $0.32 per share, showing why the two measures need different labels.
- Fourth-quarter revenue guidance of $1.19–1.20 billion is roughly flat compared with the third quarter. It implies slower annual growth of about 25–26%, making the next sales outlook more important than the latest beat alone.
- Datadog raised its annual revenue forecast to $4.52–4.525 billion from $4.45–4.47 billion. Its adjusted profit forecast also rose to $2.73–2.75 per share from $2.5–2.54.
- The outlook assumes the largest customer spends only its contractual minimum. Management also described early AI-customer renewals with better pricing, which can limit near-term revenue even as commitments grow.
- About 4,860 customers now spend at least $100,000 annually, up from 4,060 a year earlier. Growth in this group supports broader platform adoption, although large customers can still make quarterly usage uneven.
Watch customer usage, renewal pricing and the next revenue outlook. Competition and stock-based pay remain risks; the charts show November 3, before earnings and the trading-day decline.
Financials and technicals
Charts through Nov 3, 2026. The session move above may reflect later news.
Technical setup and risks
At the November 3 close of $220.52, shares were below their 20-day average near $264.31 and 50-day near $250.77. RSI, a momentum measure, was about 35.7. Prior support at $211.65–215.73 comes from November 2–3 lows, while resistance near $228.57–236.39 reflects October 30 and November 2 trading. The November 4 decline is below the earlier support band. A recovery toward it would be a stabilization test; a failed rebound would leave the trend vulnerable. These are approximate historical zones, not guaranteed turning points.
AI-assisted research with source and calculation checks. Prices may be delayed. Technical charts use the stated completed session, which can precede the quoted intraday move. Educational information; investing involves risk.