Marvell falls after agreeing to buy Lumentum in an all-stock AI connectivity deal
What is behind the stock move?
Marvell and Lumentum announced a definitive all-stock acquisition agreement on November 2, following signature on November 1. The fixed exchange ratio is 4.500 Marvell common shares per Lumentum common share. The $115 billion implied enterprise value and approximately $1,132 reference value per Lumentum share use October 28 unaffected closing prices, not a fixed cash payment or a current valuation floor. Existing Marvell holders would own approximately 67% and Lumentum holders 33% of the combined company on a fully diluted basis. The combination links Marvell’s data-infrastructure chips with Lumentum’s lasers, transceivers and optical switching. Management targets more than $1 billion annual run-rate cost savings and adjusted earnings-per-share accretion in the first year after the expected first-half-2028 closing, with approvals and integration still outstanding. Marvell shares declined during trading after the announcement; the economic tradeoff is broader optical capability against ownership dilution, execution risk and the need to realize the promised savings. The separate preliminary revenue update retains the earlier midpoint and narrows the expected range; it is not a full earnings release.
Latest company research
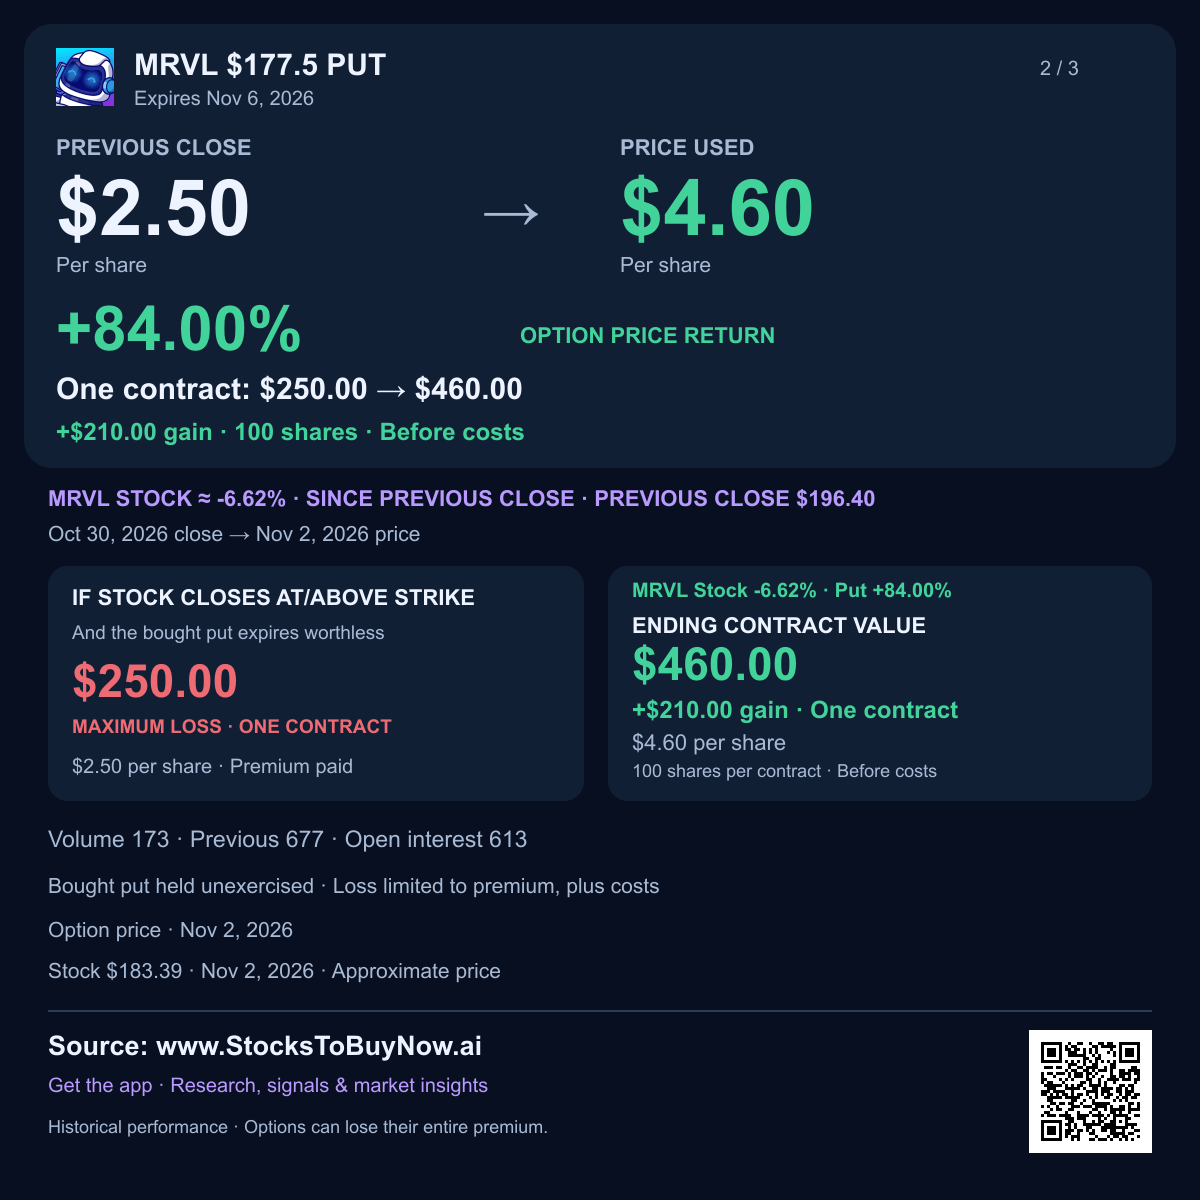
Marvell agreed to buy Lumentum in an all-stock deal announced November 2. Its shares traded at $186.61, down 4.98% during trading, as investors weighed the combination.
- The signed agreement offers 4.5 Marvell shares for each Lumentum share. The announced $115 billion enterprise value uses October 28 reference prices; the value shareholders receive will move with Marvell’s stock.
- Marvell designs chips that move data, while Lumentum supplies lasers and optical connections. Combining them could help customers connect larger AI systems with faster, more energy-efficient links.
- Current Marvell shareholders would own about 67% of the combined company and Lumentum holders about 33%. Existing investors would own a smaller share of a larger business, making the benefits of the deal crucial.
- Management expects more than $1 billion of annual cost savings and higher adjusted profit per share in the first year after closing. These are targets that depend on completing and integrating the businesses.
- Marvell also kept its earlier quarterly revenue outlook midpoint while narrowing the range. This preliminary sales update is separate from a full earnings report; the deal is expected to close in the first half of 2028, subject to shareholder and regulatory approvals.
- The completed October 30 chart closed at $196.4, below its 20-day and 50-day averages. A recovery above $214–226 would repair part of the decline; the earlier $190–196 low area is a reference to watch after the new fall.
Watch approval filings, customer commitments and progress toward the promised savings. Delays, integration costs or weaker AI spending could undermine the deal’s economics, and the chart levels are not guaranteed turning points.
Financials and technicals
Charts through Oct 30, 2026. The session move above may reflect later news.
Technical setup and risks
October 30 close $196.4; SMA20 $247.99, SMA50 $242.61, Wilder RSI14 33.96, ATR14 $17.67. October30 low190.15 and close196.40 form a prior reference area190–196, above the current intraday price following the new decline; it must not be described as confirmed support after the new decline. October29low214.56/high225.68 ground overhead214–226. Reclaiming that area would repair part of the breakdown; a close below190 extends it. Closing confirmation and merger developments matter more than assuming a rebound.
AI-assisted research with source and calculation checks. Prices may be delayed. Technical charts use the stated completed session, which can precede the quoted intraday move. Educational information; investing involves risk.